Starting an Estate Sale Business: The Complete Guide
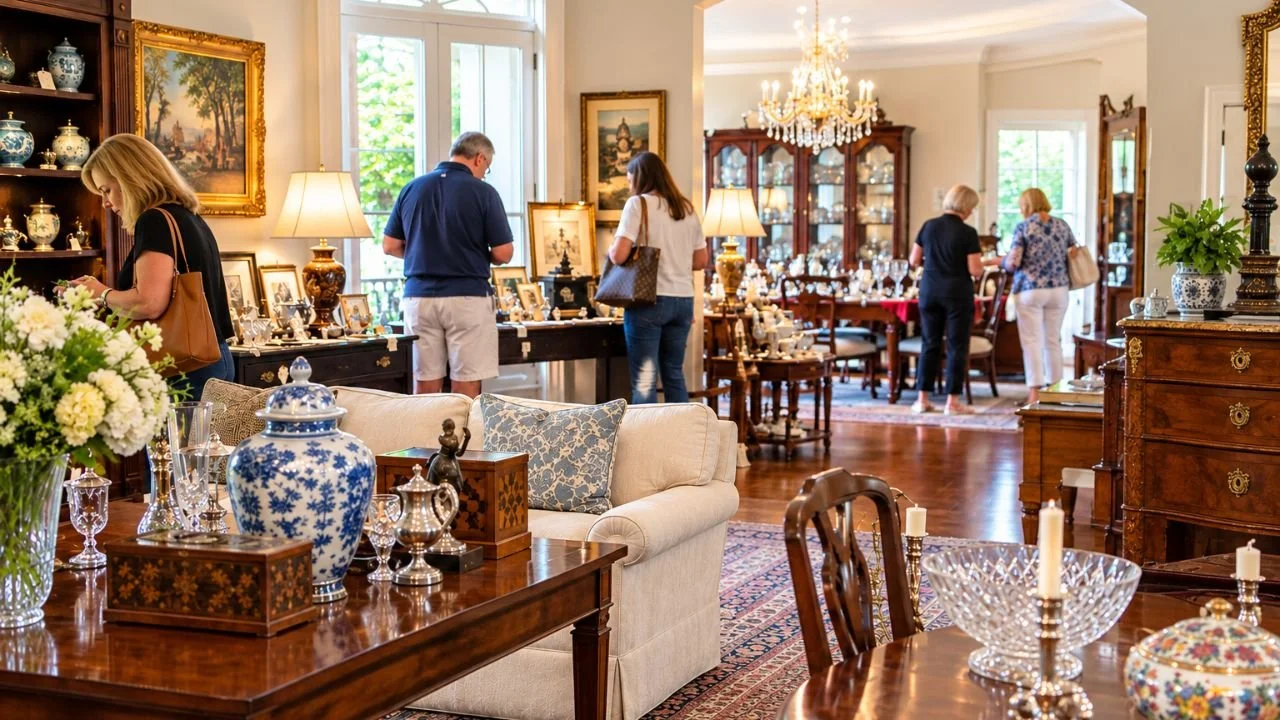
Every week, families face the same problem. A parent passes away or downsizes, and a house full of belongings needs to be sorted, priced, and sold. Most of them have no idea where to start. That gap is why estate sale companies exist, and why starting an estate sale business can be a solid path for people who love antiques, history, and hard work.
This guide shows you how to start an estate sale business, how to run it day to day, and how to organize an estate sale that earns your clients' trust. It is written from the operator's side, so expect practical steps, not theory.
An estate sale company manages the sale of most or all of the contents of a home. This is not a big yard sale. You take on the whole job: sorting, research, pricing, staging, marketing, running the sale, and clearing the house afterward. In this estate sale guide , you'll learn how companies earn a commission on what sells, and how many set a minimum fee for smaller estates. The better you price and promote, the more both you and your client earn. That shared incentive is the core of the business.
Is This Business Right for You?
Before you file any paperwork, be honest about the job. Ask yourself these questions:
Can you handle physical work? You will lift furniture, climb into attics, and stand for full sale days.
Do you enjoy research? One estate might hold mid-century furniture, costume jewelry, sterling silver, and vintage tools. You need to know what each is worth, or how to find out fast.
Are you good with people in hard moments? Many clients are grieving. Patience and tact matter as much as pricing skill.
Can you live with uneven income? Business peaks in spring and fall and slows around the holidays.
If most of your answers are yes, you have the right foundation.
How to Start an Estate Sale Business: 7 Steps
1. Learn the Trade First
The fastest way to learn is to work for someone else. Take a part-time role with an established company and work a few dozen sales. You will learn pricing, crowd control, and client handling faster than any course can teach you.
Build your knowledge on the side, too. Study sold listings on auction sites, attend local auctions, and learn the categories that drive the most value: jewelry, gold and silver, art, furniture, and collectibles. Understanding valuable items at estate sales will help you identify high-value pieces.
2. Set Up Your Legal Structure
Many estate sale companies form an LLC to separate business and personal liability. Register your business name, get an EIN from the IRS, and open a business bank account.
Then check local rules. Most states require a seller's permit or sales tax registration because you sell goods to the public. In California, for example, that means a seller's permit from the CDTFA. Some cities also require a business license or a permit for sales held in private homes. Confirm the rules in every area you plan to serve.
3. Get Insured
You will work inside other people's homes and invite strangers in. General liability insurance is the minimum. Many operators also get bonded, which tells clients their property is protected. Being insured and bonded is also a strong trust signal on your website and in consultations.
4. Write a Clear Client Contract
Your contract protects both sides. It should cover your commission rate and minimum fee, what the service includes, how unsold items are handled (donation, buyout, or cleanout), when the client gets paid, and who is responsible for the property during the sale. Have a local attorney review it once. It is a small cost that prevents large disputes.
5. Build Your Pricing Toolkit
Pricing is where estate sale companies win or lose. Set up the tools you will use every week: access to sold-price databases, a scale and acid test kit for precious metals, a jeweler's loupe, a black light, and a solid reference library. Know when to call in a specialist appraiser for fine art, rare coins, or high-end jewelry.
7. Build Your Brand and Buyer List
You need two audiences: clients who hire you and buyers who shop your sales. For clients, build a professional website, a Google Business Profile, and relationships with referral sources like real estate agents, senior move managers, and probate attorneys. For buyers, list every sale on estate sale directories and start an email list from day one. A loyal buyer list is the most valuable asset you will build.
How to Run an Estate Sale Business Day to Day
Once you are up and running, the work settles into a rhythm.
Consultations: Walk the home, assess the contents, and decide if the job is worth taking. Small, low-value estates can cost more in labor than they earn.
Team management: Most sales need three to six people for setup and sale days. Train staff on pricing rules, cash handling, and security.
Money handling: Use a point-of-sale system that records every item and payment. Estate auction services require detailed settlement reports for every client. Clear records earn referrals.
Scheduling: Book heavily in spring and fall. Use slower months for marketing, training, and building your buyer list.
Reputation: Ask every happy client for a review. In this business, reviews and referrals often beat paid ads.
How to Organize an Estate Sale: The Core Process
Every sale follows the same basic flow.
Sort and research. Go room by room. Separate items to sell, keep, donate, or discard. Check drawers, closets, and garages for hidden value.
Price everything. Research what similar items actually sold for, not what sellers are asking. Price to sell, not to sit.
Stage the home. Group similar items, clear walkways, and keep high-value pieces in a secure, supervised area.
Photograph and promote. Post clear photos on estate sale sites, your website, social media, and your email list at least a week ahead.
Run the sale. Control entry with a sign-in list or numbers, staff every room, and set a clear discount plan for later days.
Settle and clear out. Handle unsold items as your contract states, leave the home broom-clean, and deliver the final report and payment.
Common Mistakes New Owners Make
Under pricing out of fear. Low prices cost your client money and hurt your reputation.
Skipping the contract. Handshake deals lead to disputes.
Taking every job. Low-value estates drain time you could spend on better ones.
Ignoring buyers. Without repeat buyers, every sale starts from zero.
Weak security. Theft is a real risk. Staff every room and lock up small valuables.
Avoiding common estate auction mistakes helps new owners protect their clients' belongings, manage sales efficiently, and build a trustworthy reputation.
Final Thoughts
Starting an estate sale business takes more than a love of old things. It takes pricing skill, solid systems, and the trust of families during hard transitions. Learn from experienced operators, set up your legal and financial base properly, and build a buyer list from your very first sale. Do that, and you will have a business that grows through referrals and repeat buyers.